内容概括
投资组合优化需要适应动态市场,而常规强化学习的奖励设计难以刻画市场的复杂性,现有方法也缺少对金融知识的系统整合。论文提出启发式引导的逆强化学习框架:生成兼顾行业分散与相关性约束的专家策略,以多目标奖励优化在收益与风险之间自适应平衡,并用带层次注意力的异构图策略学习显式建模股票间关系。实验基于真实金融市场数据,并通过案例分析考察框架在收益最大化与风险控制之间的平衡。
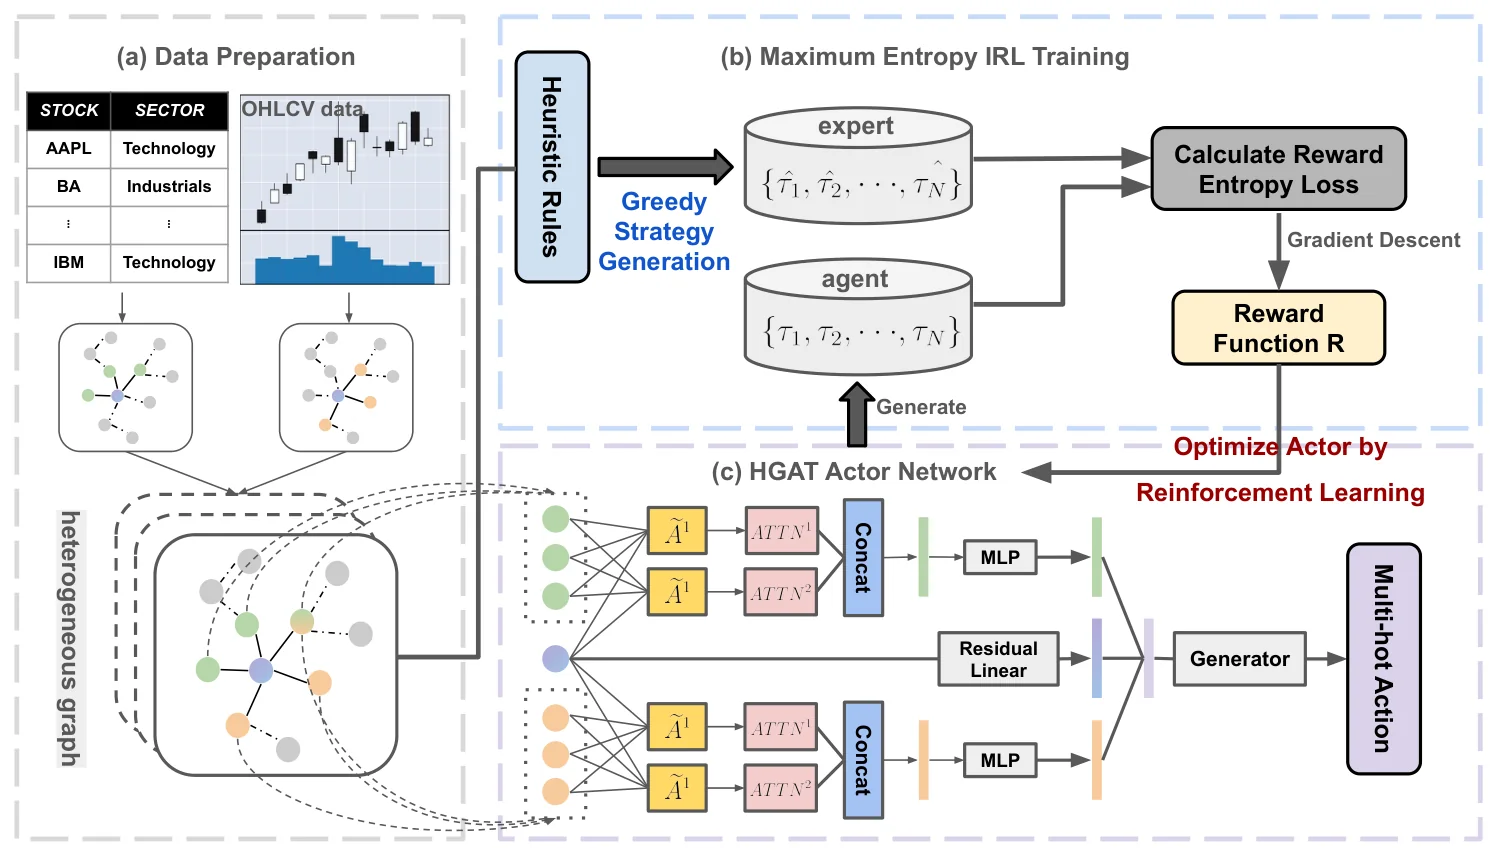
投资组合优化需要适应动态市场,而常规强化学习的奖励设计难以刻画市场的复杂性,现有方法也缺少对金融知识的系统整合。论文提出启发式引导的逆强化学习框架:生成兼顾行业分散与相关性约束的专家策略,以多目标奖励优化在收益与风险之间自适应平衡,并用带层次注意力的异构图策略学习显式建模股票间关系。实验基于真实金融市场数据,并通过案例分析考察框架在收益最大化与风险控制之间的平衡。
Portfolio optimization faces persistent challenges in adapting to dynamic market environments due to its dependence on static assumptions and high-dimensional decision spaces. Although reinforcement learning (RL) has emerged as a promising solution, conventional reward engineering methods often struggle to capture the complexities of market dynamics. Recent advances in deep RL and graph neural networks (GNNs) have sought to enhance market microstructure modeling. However, these methods still struggle with the systematic integration of financial knowledge. To address the above issues, we propose a novel heuristic-guided inverse RL framework for portfolio optimization. Specifically, our framework provides an effective mechanism for generating expert strategies that takes into account sector diversification and correlation constraints. Then, it employs a multi-objective reward optimization method to strike an adaptive balance between returns and risks. Furthermore, it utilizes heterogeneous graph policy learning with hierarchical attention mechanisms to model inter-stock relationships explicitly. Finally, we conduct extensive experiments on real-world financial market data to demonstrate that our framework outperforms several state-of-the-art baselines in terms of risk-adjusted returns. We also provide case studies to demonstrate the effectiveness of our framework in balancing return maximization and risk containment. Our code and data are publicly available at https://github.com/ChloeWenyiZhang/SmartFolio/.
来源:IJCAI 2025 · 原文摘要