内容概括
现有信用风险模型多将每家银行独立评估,忽视了银行间日益紧密的关联。HFTCRNet 由长期时序、短期跨图、注意力风险传染与层次融合四个 Transformer 模块组成,分别刻画银行的长期成长轨迹、银行间网络的短期变化以及风险在网络中的潜在传播,并逐层融合。作者构建了覆盖 4548 家银行、2016Q1–2023Q1 的银行间信用评级数据集,以半监督方式联合信用评级与 SRISK 指标,同时评估单家银行的信用状况与银行间系统性风险。
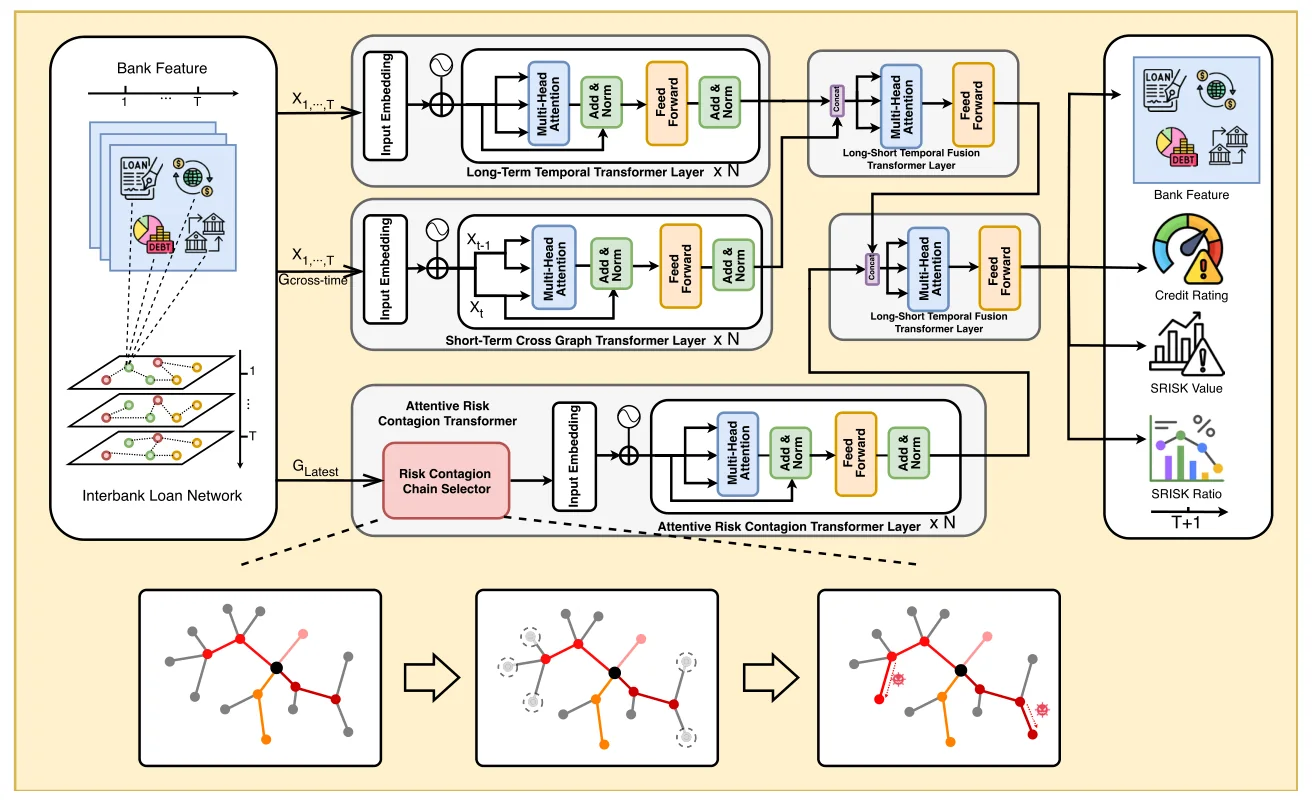
现有信用风险模型多将每家银行独立评估,忽视了银行间日益紧密的关联。HFTCRNet 由长期时序、短期跨图、注意力风险传染与层次融合四个 Transformer 模块组成,分别刻画银行的长期成长轨迹、银行间网络的短期变化以及风险在网络中的潜在传播,并逐层融合。作者构建了覆盖 4548 家银行、2016Q1–2023Q1 的银行间信用评级数据集,以半监督方式联合信用评级与 SRISK 指标,同时评估单家银行的信用状况与银行间系统性风险。
As a prominent application of deep neural networks in financial literature, bank credit ratings play a pivotal role in safeguarding global economic stability and preventing crises. In the contemporary financial system, interconnectivity among banks has reached unprecedented levels. However, many existing credit risk models continue to assess each bank independently, resulting in inevitable suboptimal performance. Thus, developing advanced neural networks to model intricate temporal dynamics and interconnected relationships in the banking system is essential for an effective credit rating and risk assessment learning system. To this end, we propose a novel hierarchical fusion transformer for interbank credit rating and risk assessment (HFTCRNet), which includes the long-term temporal transformer (LT3) module, short-term cross-graph transformer (STCGT) module, attentive risk contagion transformer (ARCT) module, and hierarchical fusion transformer (HFT) module to capture the long-term growth trajectories of banks, the short-term interbank network variance, the potential propagation of risks within interbank network, and integrate these information hierarchically. We further develop an interbank credit rating dataset, encompassing quarterly financial data, interbank lending networks, and key indicators such as credit ratings and systemic risk (SRISK) for 4548 banks from 2016Q1 to 2023Q1. Notably, we also adapt the minimum density algorithm to stabilize the interbank loan network over time, aiding in the analysis of long-term and short-term network effects. Our learning system uses semi-supervised learning to handle labels of varying sparsity, integrating credit ratings and SRISK for a comprehensive assessment of individual bank creditworthiness and systemic interbank risk. Extensive experimental results on our interbank dataset show that HFTCRNet not only outperforms all the baselines in terms of credit rating accuracy but also can evaluate the systemic risk within the interbank network. Code will be available at: https://github.com/AI4Risk/HFTCRNet.
来源:TNNLS 2024 · 原文摘要