内容概括
网络化贷款是部分发展中国家中小微企业的重要融资方式,外部冲击下一次意外违约可能沿网络扩散,进而波及整个网络。论文提出结合深度强化学习与高阶图消息传递网络的方法 SCRPF,预测网络化贷款中的关键企业,以阻断传染风险;在一家大型商业银行的数据集上进行了实验,并基于真实贷款数据开展了风险缓释的实证研究。
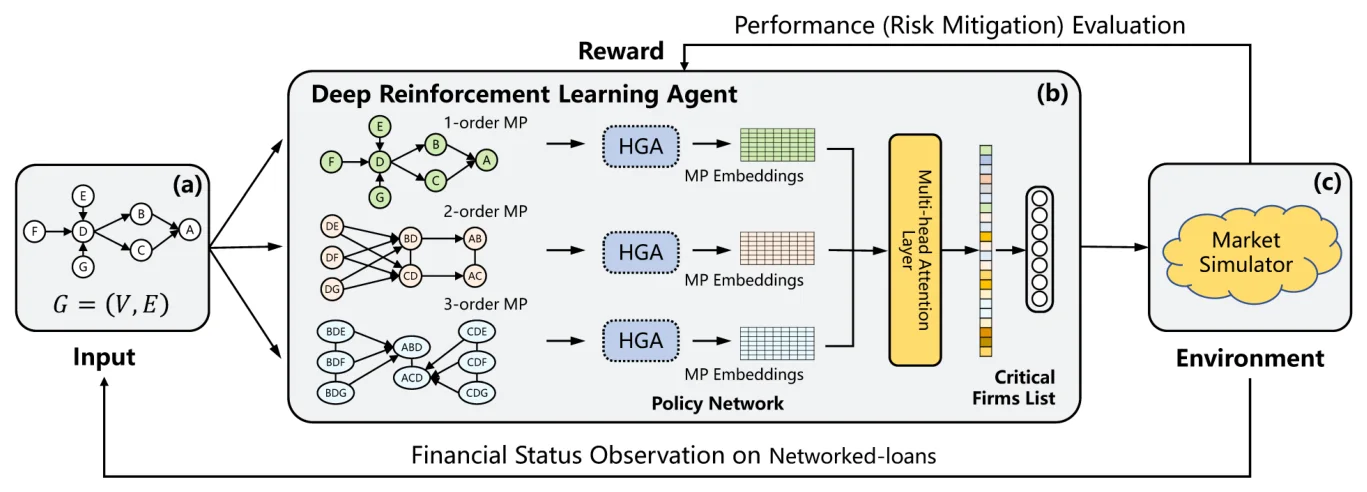
网络化贷款是部分发展中国家中小微企业的重要融资方式,外部冲击下一次意外违约可能沿网络扩散,进而波及整个网络。论文提出结合深度强化学习与高阶图消息传递网络的方法 SCRPF,预测网络化贷款中的关键企业,以阻断传染风险;在一家大型商业银行的数据集上进行了实验,并基于真实贷款数据开展了风险缓释的实证研究。
The networked-loan is major financing support for Micro, Small and Medium-sized Enterprises (MSMEs) in some developing countries. But external shocks may weaken the financial networks’ robustness; an accidental default may spread across the network and collapse the whole network. Thus, predicting the critical firms in networked-loans to stem contagion risk and prevent potential systemic financial crises is of crucial significance to the long-term health of inclusive finance and sustainable economic development. Existing approaches in the banking industry dismiss the contagion risk across loan networks and need extensive knowledge with sophisticated financial expertise. Regarding the issues, we propose a novel approach to predict critical firms for stemming contagion risk in the bank industry with deep reinforcement learning integrated with high-order graph message-passing networks. We demonstrate that our approach outperforms the state-of-the-art baselines significantly on the dataset from a large commercial bank. Moreover, we also conducted empirical studies on the real-world loan dataset for risk mitigation. The proposed approach enables financial regulators and risk managers to better track and understands contagion and systemic risk in networked-loans. The superior performance also represents a paradigm shift in addressing the modern challenges in financing support of MSMEs and sustainable economic development.
来源:AAAI 2023 · 原文摘要